For many entrepreneurs, building a successful company represents years of dedication, financial sacrifice, and calculated decisions. Business owners often reinvest profits, expand operations, hire employees, and focus on strengthening their company’s long-term position.
However, business success and personal financial security are not necessarily the same thing.
A profitable company may represent substantial wealth on paper, but that wealth is not always readily available to support personal expenses, retirement, or unexpected financial needs.
For Canadian business owners, incorporated professionals, and executives, developing a personal financial plan alongside business growth can help create greater financial flexibility.
The objective is not to reduce commitment to the business. It is to ensure that personal financial goals receive the same thoughtful attention as business operations.
Understanding the Difference Between Business Wealth and Personal Wealth
One of the most important financial distinctions for entrepreneurs is understanding the difference between owning a valuable business and having accessible personal assets.
Business wealth may include company shares, equipment, retained earnings, property, and other assets used in operations.
Personal wealth generally includes assets owned individually, such as savings, investments, retirement accounts, and personal real estate.
For example, an entrepreneur may own shares in a successful company but have relatively little money invested outside the business.
If the company experiences financial difficulties or cannot be sold under favourable conditions, the owner’s personal financial circumstances may be affected.
Recognizing this distinction can encourage business owners to consider building financial resources beyond their company’s value.
Why Separating Personal and Business Finances Matters
Maintaining clear financial boundaries helps business owners understand their actual financial position.
This is particularly important for incorporated professionals and entrepreneurs who manage both corporate and personal expenses.
Establish Clear Financial Records
Separate accounts and accurate bookkeeping can help distinguish business transactions from personal spending.
They also make it easier to evaluate the company’s financial performance without confusing operating expenses with household needs.
Develop a Personal Spending Plan
Business owners should understand how much money their household requires for housing, transportation, family responsibilities, and other expenses.
A personal budget provides a clearer picture of the income needed outside the company.
Review Compensation Arrangements
Incorporated business owners may receive compensation through salary, dividends, or other arrangements.
Each option can involve different tax and financial planning considerations.
A qualified accountant can help evaluate compensation decisions according to the owner’s circumstances.
Building Personal Savings Outside the Business
Entrepreneurs often prioritize reinvesting available funds into their companies.
While reinvestment may support business objectives, relying entirely on business equity can concentrate financial exposure.
Developing personal savings provides another source of financial flexibility.
For example, a business owner might establish a regular savings arrangement funded through appropriate personal compensation.
Depending on eligibility and circumstances, Canadian financial planning options may include Registered Retirement Savings Plans (RRSPs), Tax-Free Savings Accounts (TFSAs), and other investment accounts.
These accounts have different contribution rules and tax considerations.
A suitable savings strategy depends on personal income, available resources, investment objectives, and risk tolerance.
The goal is to build financial resources that do not depend exclusively on the future performance or sale of the company.
Planning for Retirement Without Depending Entirely on a Business Sale
Some entrepreneurs expect the eventual sale of their company to fund retirement.
However, business sale proceeds can be uncertain.
Market conditions, buyer interest, business performance, ownership agreements, and transaction expenses may influence the amount an owner ultimately receives.
Retirement planning should therefore consider more than an anticipated sale price.
Estimate Future Lifestyle Needs
Business owners can begin by identifying expected retirement expenses, including housing, healthcare, travel, and family responsibilities.
Review Potential Income Sources
Retirement income may come from personal investments, registered accounts, government benefits, and business-related proceeds.
Consider Different Retirement Scenarios
A business owner may retire gradually, reduce responsibilities, transfer ownership, or sell the company.
Each possibility creates different financial considerations.
Professional financial planning for business owners can help connect retirement objectives with broader personal and corporate financial decisions.
Preparing for Unexpected Business Interruptions
Even established businesses can face unexpected challenges.
Economic changes, customer losses, equipment failures, health concerns, and operational disruptions may affect company revenue.
For owners whose household income depends heavily on the business, these interruptions can create personal financial pressure.
A practical contingency plan may involve maintaining appropriate cash reserves, reviewing insurance needs, and understanding existing financial obligations.
For example, an entrepreneur who cannot work temporarily may need to consider how household expenses and business responsibilities would be managed.
The appropriate arrangements depend on the company’s structure and the owner’s circumstances.
Planning for uncertainty does not eliminate financial risk, but it can help identify potential vulnerabilities before they become urgent.
Understanding Cash Flow, Debt, and Investment Priorities
Financial planning requires attention to how money moves between business operations and personal life.
A company may generate substantial revenue while also carrying significant expenses, debt obligations, or working capital requirements.
Similarly, a business owner may have valuable personal assets but limited accessible cash.
Review Cash Flow Regularly
Business owners should understand their expected income, recurring obligations, and available financial resources.
Evaluate Debt Responsibilities
Business loans, mortgages, and other financial commitments can influence flexibility.
Owners should also understand any personal guarantees associated with business borrowing.
Balance Saving and Investing
Investment decisions should reflect financial goals, time horizons, liquidity requirements, and tolerance for risk.
Rather than focusing exclusively on potential investment returns, entrepreneurs can consider how different financial resources support their long-term plans.
Preparing for Business Succession and an Eventual Exit
Business succession planning involves considering what will happen when the current owner reduces involvement or leaves the company.
Some entrepreneurs hope to transfer ownership to family members. Others may sell to employees, business partners, or outside buyers.
These possibilities involve different operational, financial, and legal considerations.
A business succession plan may address ownership arrangements, leadership responsibilities, business valuation, and the owner’s future income needs.
The Government of Canada’s business planning resources provide guidance on business structures, financing, and other planning considerations relevant to entrepreneurship.
Owners should also recognize that succession discussions may need to begin well before an anticipated exit.
Early preparation allows time to evaluate options and coordinate with appropriate professionals.
Working With Qualified Financial and Tax Professionals
Business owners often manage several interconnected financial responsibilities.
Corporate investments, personal savings, tax obligations, insurance, estate planning, and retirement decisions can influence one another.
For this reason, professional advice may involve collaboration between financial planners, accountants, legal professionals, and investment specialists.
For example, a decision about how much money to retain within a corporation may affect investment planning, personal compensation, and future tax obligations.
Organizations such as Exponent Investment Management work with Canadian business owners and professionals on financial planning and investment management considerations.
When choosing advisers, entrepreneurs should review qualifications, relevant experience, fees, and the services provided.
No financial strategy can guarantee investment performance or complete financial independence.
Creating a Practical Personal Financial Planning Routine
Business owners can begin strengthening their personal finances through a manageable review process.
Useful steps include:
- Identify personal financial goals: Define priorities involving retirement, family responsibilities, and financial flexibility.
- Review assets and liabilities: Understand what is owned personally and what remains tied to the business.
- Evaluate cash reserves: Consider available resources for unexpected expenses or income interruptions.
- Review retirement arrangements: Examine existing savings and potential future income sources.
- Discuss succession planning: Identify possible ownership transitions and related financial considerations.
- Schedule professional reviews: Revisit plans when business circumstances or personal priorities change.
Regular reviews help keep financial decisions connected to current circumstances rather than outdated assumptions.
Building Financial Independence Alongside Business Growth
Building a successful business is an important achievement, but it represents only one part of an entrepreneur’s financial life.
Personal financial security also depends on accessible savings, manageable obligations, appropriate investments, retirement preparation, and contingency planning.
A business owner who develops these areas alongside company growth may gain greater flexibility when making future decisions.
The objective is not to separate business success from personal financial goals completely. It is to ensure that the two are thoughtfully coordinated.
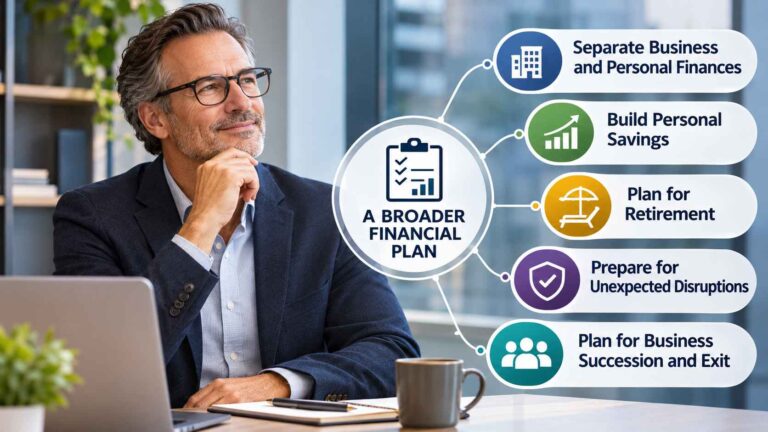
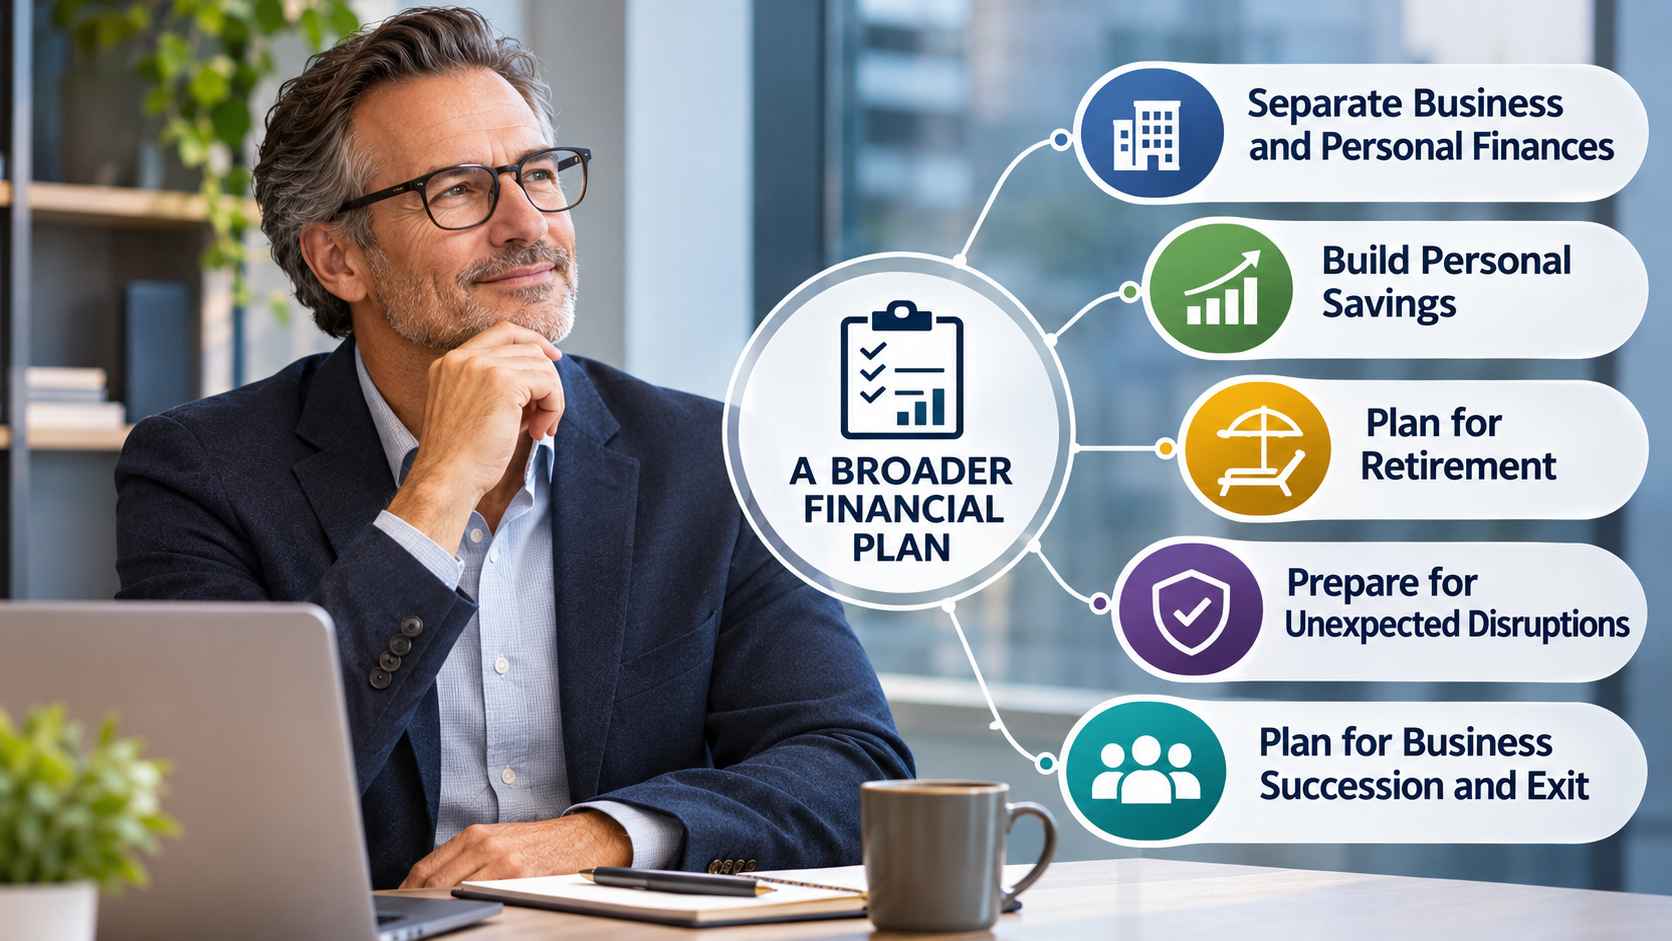
By understanding the difference between corporate and personal wealth, preparing for uncertainty, and working with qualified professionals, entrepreneurs can develop a broader financial plan that supports both their business ambitions and their lives beyond the company.
About the Author